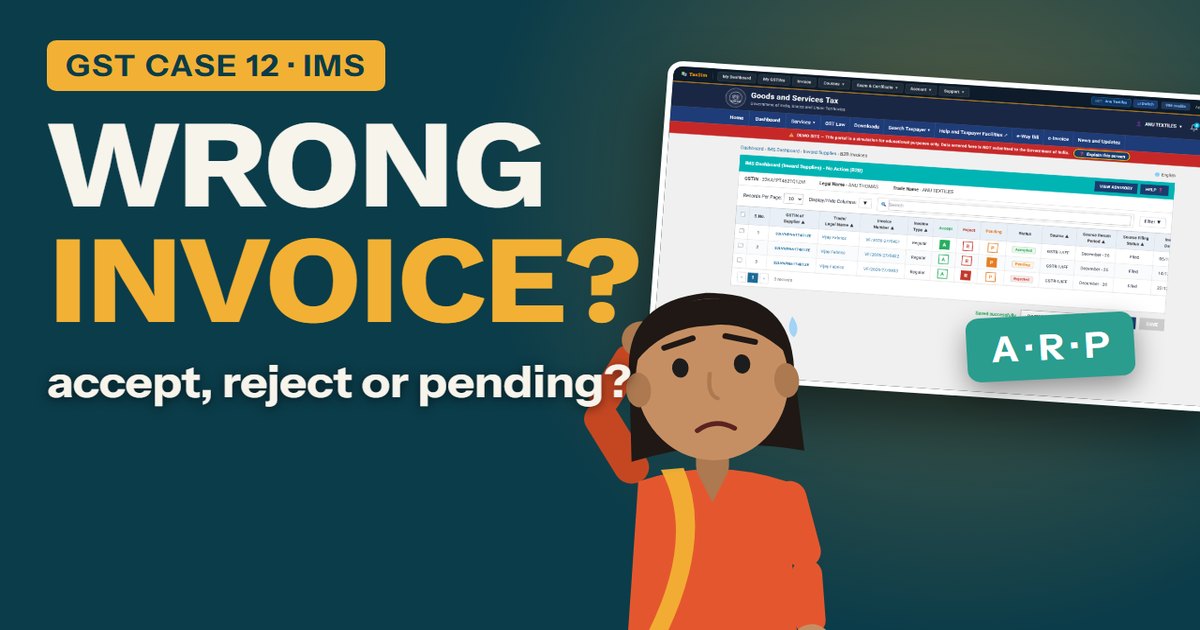
Short answer: Accept an invoice that is correct, keep it Pending if you are still checking, and Reject one that is wrong. If you take no action, it is deemed accepted when GSTR-2B is generated.
What each IMS action does
| Action | Effect |
|---|---|
| Accept | ITC available in GSTR-2B |
| Reject | No ITC. The supplier sees it and must correct it |
| Pending | Stays out of this GSTR-2B. Decide in a later month, within the ITC time limit |
| No action | Deemed accepted |
Example: three invoices from one supplier
- ₹1,50,000, goods received: Accept. GST ₹27,000.
- ₹80,000, agreed price was ₹60,000: Pending, while checking with the supplier.
- ₹1,50,000, same delivery billed again: Reject.
With no action, ₹68,400 would have entered GSTR-2B. After these decisions, only ₹27,000 does.
Does accepting make the credit safe?
No. Blocked credit under Section 17(5) stays blocked even after acceptance, and Section 16(2)(b) still requires that you actually received the goods or services.
Practise it before you need it
You can try IMS actions on IndIaTaxSim, an educational GST simulator. Nothing you enter goes to the real portal, and all the data is demo data. Your first practice GST registration is free, and course Modules 1, 2 and 10 are free to watch.
This page is general education, not tax or legal advice for your own case. For real filings, use the official GST portals.
📚 Continue Learning
📖 You Might Also Like
IndIaTaxSim Team
GST compliance experts building India's most complete GST simulation platform. All articles are reviewed for accuracy against the latest GSTN portal updates.