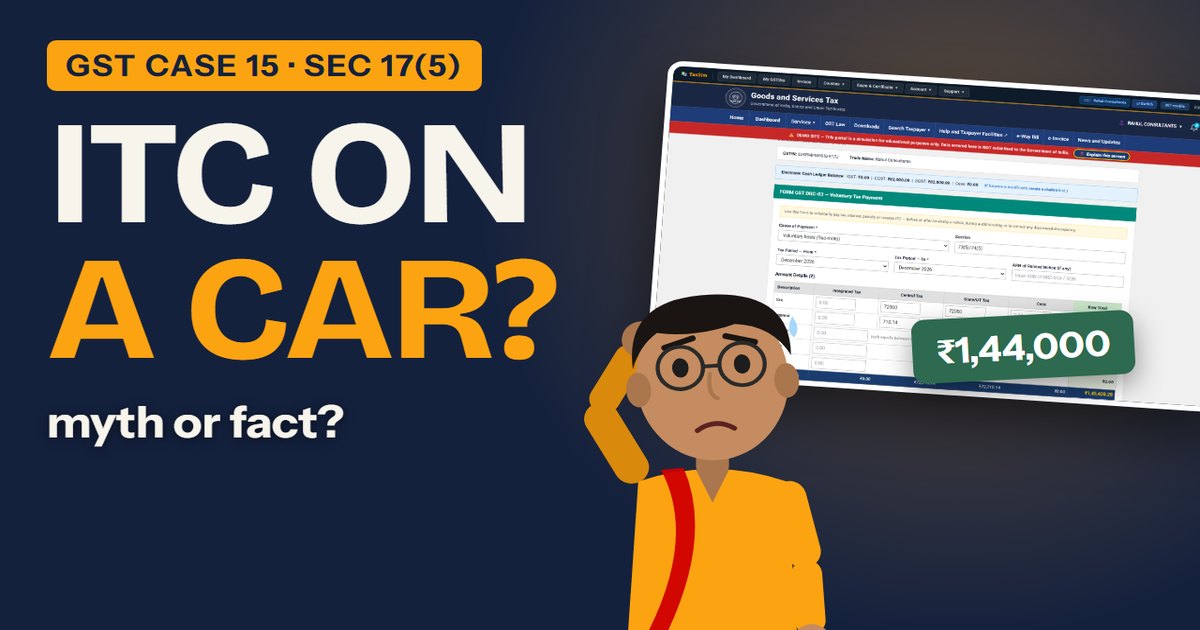
Short answer: using a car for business does not by itself allow ITC. Section 17(5)(a) blocks credit on motor vehicles for passengers with up to 13 seats, including the driver. If you wrongly claimed it and used it, pay it back with 18% interest through DRC-03.
Who can claim ITC on a car?
| Business | ITC on the car |
|---|---|
| Car dealer, for further supply | Allowed |
| Taxi or passenger transport operator | Allowed |
| Driving school | Allowed |
| Consultant, doctor or shop | Blocked |
Why did GSTR-2B show it?
GSTR-2B reports what suppliers filed. It does not decide whether the credit is blocked for you. That check is yours.
Example: ₹1,44,000 wrongly claimed
A consultant buys a car for ₹8,00,000 + 18% GST (car rates vary) and uses ₹72,000 CGST + ₹72,000 SGST of credit in December's GSTR-3B. The mistake is found on 9 February. Taking the 20 January due date as the date of use:
- Interest: ₹72,000 × 18% × 20 ÷ 365 = ₹710.14 under each head.
- Total through DRC-03: ₹1,44,000 + ₹1,420.28 = ₹1,45,420.28.
In the books, the blocked GST becomes part of the cost of the car.
What else is blocked?
With limited exceptions, Section 17(5) also covers food and catering, beauty treatment, club memberships, health insurance, construction of your own building, gifts, free samples and personal use.
Practise it before you need it
You can try a voluntary DRC-03 payment on IndIaTaxSim, an educational GST simulator. Nothing you enter goes to the real portal, and all the data is demo data. Your first practice GST registration is free, and course Modules 1, 2 and 10 are free to watch.
This page is general education, not tax or legal advice for your own case. For real filings, use the official GST portals.
📖 You Might Also Like
IndIaTaxSim Team
GST compliance experts building India's most complete GST simulation platform. All articles are reviewed for accuracy against the latest GSTN portal updates.